All Categories
Featured


Reviewing Individual Health Quotes
Among the most appealing features is the ability to access the cash worth through policy loans and withdrawals, typically on a tax-free basis, supplied the policy is structured correctly and stays in force. Policy loans are generally not thought about taxable income. Withdrawals as much as the amount of premiums paid (your expense basis) are usually tax-free.
Insurance in Hemet CAHowever, it's important to understand that if the policy lapses or is surrendered, impressive loans and gains may end up being taxable. The adjustable premium payments and possible survivor benefit alternatives supply a degree of flexibility not always found in other permanent life insurance items. While concentrating on cash growth, the policy still provides an important death advantage for beneficiaries, offering financial protection for your enjoyed ones.
The "finest IUL policies for money accumulation" will normally include competitive caps, involvement rates, and manageable internal expenses. The "finest company for IUL" for retirement preparation may likewise use beneficial loan provisions. But keep in mind, these features should be examined together. A high cap may be offset by high fees or a low participation rate.
Since today's cap is not the entire story, our contrast of IUL renewal cap rates: F&G vs Pacific Life and Lincoln looks at how caps have actually altered over time. While IUL provides engaging possible advantages, it's important to approach it with a clear understanding of the associated risks and costs.
Direct Insurance Advice for Selecting Coverage
IUL policies are inherently more intricate than term life or even conventional whole life. Policy illustrations, which project future money worth growth, are based on various presumptions about index efficiency, crediting rates, policy costs, and loan use.
Insurance in Hemet CAIUL policies have different internal charges that reduce money worth growth. These can consist of: The charge for the pure death advantage protection.
Expenses for any fringe benefits contributed to the policy. Costs applied if you surrender the policy or withdraw considerable amounts, normally within the very first 10-15 years. These expenses are deducted no matter index efficiency. High internal expenses can considerably hinder money value accumulation, especially in years with low or zero interest crediting.
While the floor secures against direct market * losses *, it does not guarantee favorable returns. If the connected index performs badly or remains flat for prolonged durations, your money worth may just make the floor rate (typically 0%). After policy expenses are deducted, the money worth might potentially reduce in such years.
Even in booming market years, your credited interest will not exceed the cap. Participation rates listed below 100% additional reduce the credited interest relative to the index gain. Providers can often adjust non-guaranteed aspects like caps and involvement rates over the life of the policy (within legal limitations), which might impact long-lasting efficiency.

Latest Posts
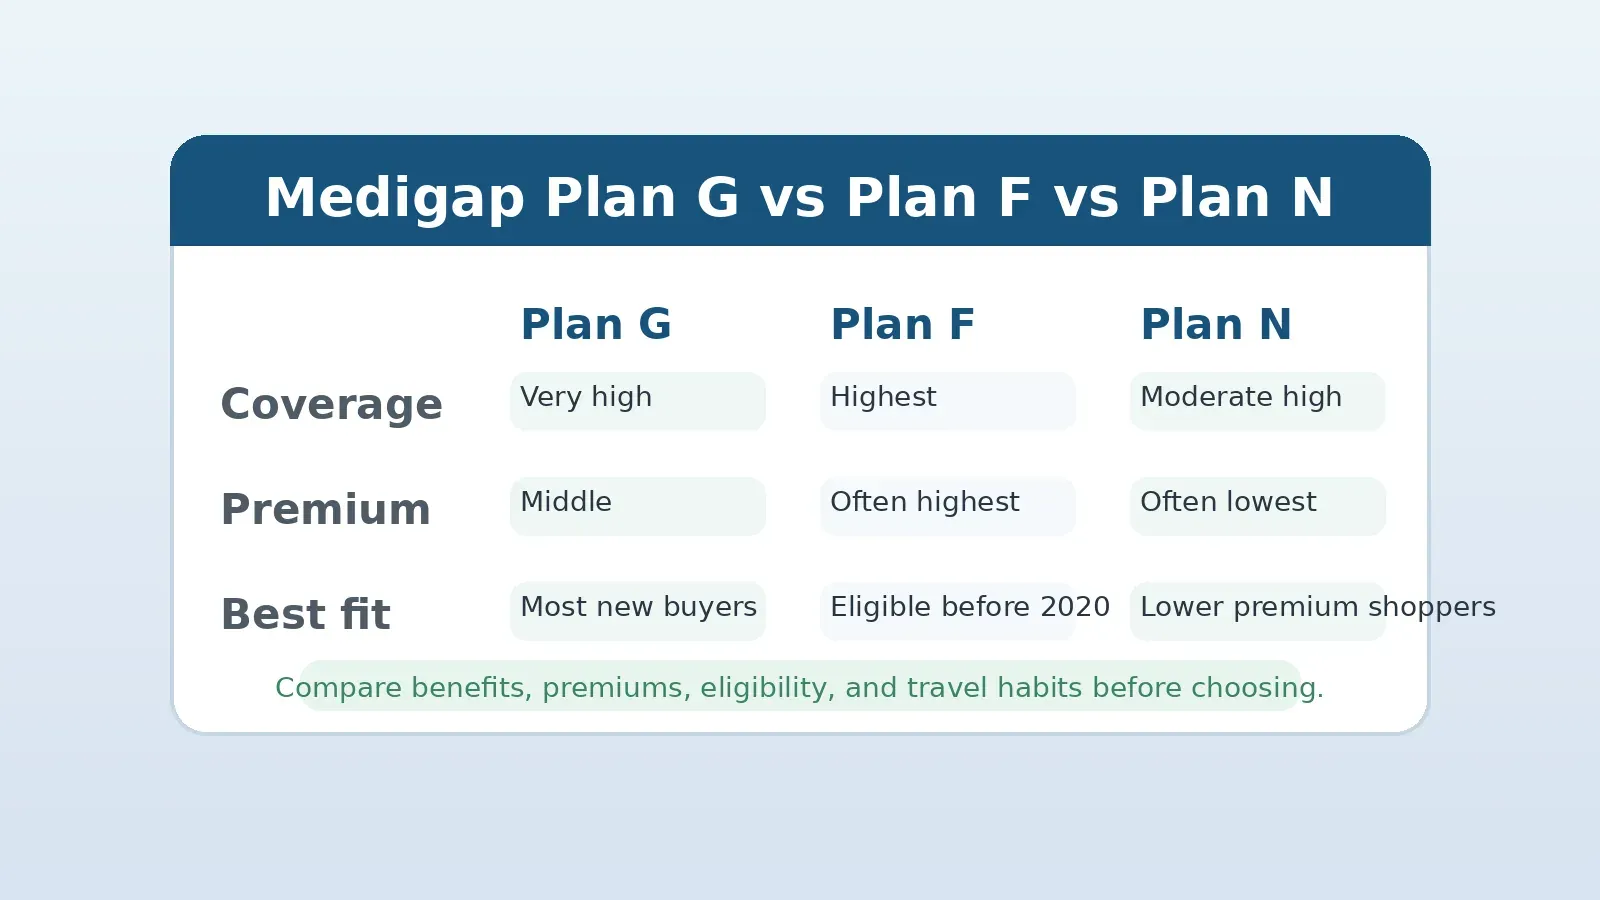
Boosting Your Benefits with Local Supplemental Insurance

Veteran-Specific Health and Life Insurance Needs in South Gate
Reviewing 2026 Individual Medical Quotes